
Kevin Carter/Getty Images
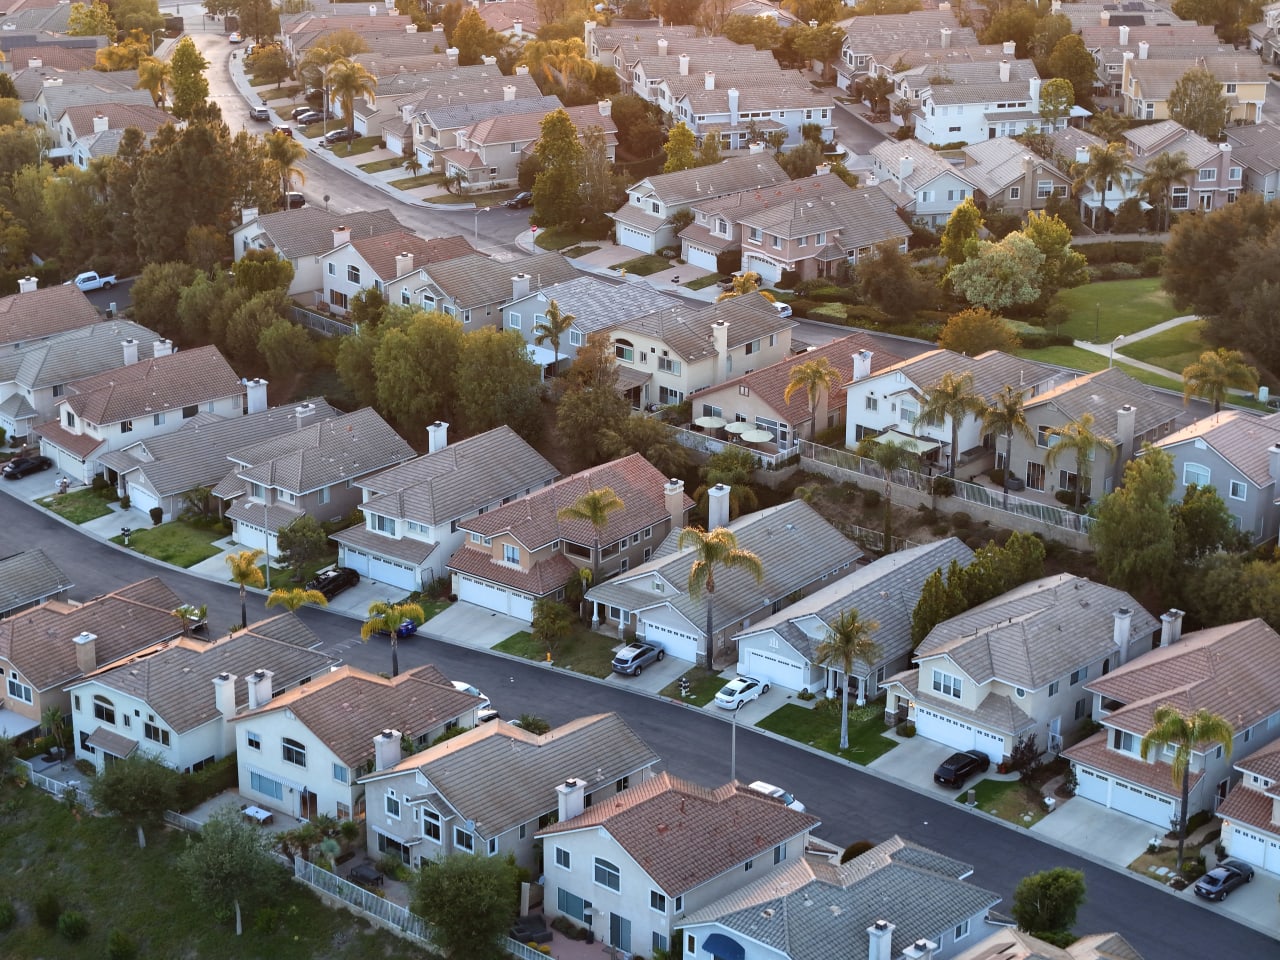
Higher mortgage rates have slowed some markets, giving buyers more room to negotiate with sellers.
A seller-funded temporary rate buydown can lower a buyer’s mortgage payments for the first few years.
Buyers should make sure they can afford the full monthly payment once the temporary discount expires.
Mortgage rates have climbed rapidly in recent weeks , slowing homebuying activity in markets across the US.
“Everybody moves together. And the market is so cyclical. It’s like this almost herd mentality,” real estate investor and agent Dana Bull told Business Insider. The recent run-up, she said, has brought activity in her Boston-area market to “a screeching halt.”
The average 30-year fixed mortgage rate was hovering around 7.4% in early October, according to Freddie Mac — its highest level in about three years.
Bull’s advice: Don’t let high rates alone stop you from making an offer.
“We have to start going into problem-solving mode,” she said. “Okay, what is the issue here? Is it the price of the property? Is it the interest rate? What solutions do we have available to overcome those hurdles?”
Dana Bull is a real-estate agent, investor, and consultant.
Courtesy of Dana Bull
One tool in that toolbox, Bull said, is a seller-funded temporary rate buydown.
How a temporary rate buydown works
A temporary rate buydown lets a buyer pay a lower mortgage rate for the first few years after buying a home. The seller helps cover the difference.
Here’s how it works: During negotiations, the buyer asks the seller for a credit at closing. Instead of using that credit only for typical closing costs, the buyer uses it to lower their mortgage payments for a set period.
For example, a seller might agree to provide a $15,000 credit. That money is set aside to subsidize the buyer’s payments during the buydown period. The exact monthly savings will depend on the loan amount, the original interest rate, and the type of buydown, though Bull said they could be significant.
A common option is called a 2-1 buydown. If the buyer’s original mortgage rate is 7.5%, they would pay a 5.5% rate in the first year — two percentage points lower than their original rate. In the second year, they would pay 6.5%. Starting in year three, they would pay the full 7.5% rate for the rest of the loan, unless they refinance.
The strategy can give new homeowners some breathing room while they rebuild cash reserves after closing or adjust to other early ownership costs, Bull said: “They can be really helpful for people that just need a little bit of cushioning in those early years.”
She and her clients bring up the idea of a buydown when a listing is less competitive, has been sitting on the market, or the seller is particularly motivated.
“It’s not always something that you can negotiate, and it doesn’t always make sense,” Bull said. “But there are definitely situations where we’re doing it because, why not?”
A buydown can reduce payments — but it isn’t a permanent rate cut
The mortgage still carries its original note rate, which takes effect once the temporary discount expires. Buyers should be able to comfortably afford that full payment before moving forward.
Nor should buyers assume they’ll be able to refinance before the buydown ends. Rates could fall, remain elevated, or move higher. Still, refinancing at a lower rate is the ideal outcome for some buyers who use the strategy.
“You are rolling the dice a little bit, and hoping that over the next couple of years, maybe interest rates dip at some point and you can refinance,” Bull said.
Read the original article on Business Insider